

Australia’s card payments sector plays a central role in everyday purchases, online shopping, travel bookings and business transactions. Consumers expect payment methods to be convenient, secure and widely accepted, while merchants need reliable processing systems and transparent costs. According to a Vyansa Intelligence report, Australia’s cards payments market is valued at $860.17 Billion in 2025 and is projected to reach $1025.35 Billion by 2032, with a CAGR of 2.54% from 2026 to 2032.
Digital Payments Become Part of Everyday Life
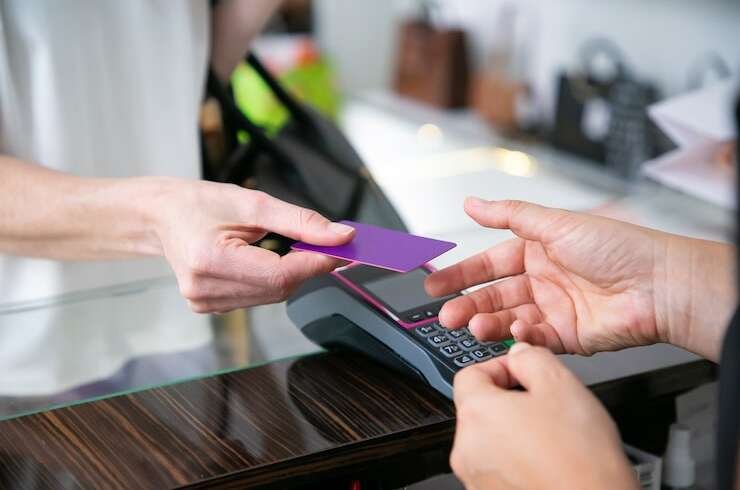
Card payments are integrated into a wide range of consumer activities, from supermarket purchases and dining to transport, accommodation and online retail. Contactless transactions allow customers to pay without handling cash, while digital wallets let users make payments through compatible mobile devices and wearables. These options have made the checkout experience more flexible for consumers and businesses.
The Reserve Bank of Australia’s analysis, Consumer Payment Behaviour in Australia, discusses the continued importance of cards and the increasing use of device-based payments. The findings highlight how consumer expectations are shaped by payment methods that are quick to use and widely accepted.
Industry analysis needs to consider more than transaction convenience. Customers also expect consistent performance across physical stores, websites and mobile applications. Merchants, meanwhile, need payment systems that integrate with sales platforms, support reconciliation and provide dependable transaction records.
Contactless Payments and Digital Wallets
Consumers increasingly expect to move between physical cards and digital payment options without changing their overall purchasing experience. Digital wallets can reduce the need to carry a physical card, while tokenisation can help protect sensitive payment information during transactions. These technologies also create opportunities for businesses to streamline checkout processes and offer more consistent payment experiences across sales channels.
In this report, a key consideration is how payment providers balance convenience with security. Customers benefit when transactions are easy to complete, but they also need confidence that their information is protected and that payment errors can be resolved. Clear transaction notifications, accessible receipts and straightforward dispute processes can strengthen that confidence.
Businesses should also consider accessibility. Not every customer uses the same device or prefers the same payment method. Supporting a practical range of payment options can help merchants serve customers with different preferences while maintaining a consistent checkout process.
Transparency and Consumer Confidence
Payment fees influence both merchant decisions and customer perceptions. Consumers want to know the amount they will pay before completing a purchase, while businesses need to understand the costs associated with accepting different card types and processing transactions.
The Australian Competition and Consumer Commission explains the relevant requirements in its guidance on card surcharges. As of October 2026, card payment surcharges are no longer permitted under the new card-network rules described by the regulator. Businesses may incorporate payment acceptance costs into their overall prices, but must not mislead customers about prices or the reasons for price changes.
A Market research report examining card payments should therefore consider pricing transparency alongside payment technology. Clear total prices, understandable receipts and accessible explanations of fees can help consumers make informed choices. Merchants also need to review their checkout displays and payment arrangements to ensure that customer-facing information reflects the applicable rules.
Security, Reliability and Fraud Prevention
As card payments span in-store terminals, e-commerce websites and mobile applications, security remains a core requirement. Payment providers and merchants need to protect transaction information, monitor suspicious activity and ensure that payment systems remain reliable.
Tokenisation, authentication controls and transaction monitoring can help reduce exposure to payment data and identify potentially unauthorised activity. However, technical safeguards need to be supported by effective operational processes. Customers should have clear instructions for reporting suspicious transactions, while businesses need procedures for investigating payment disputes and managing service interruptions.
Latest market analysis should also account for the customer experience when something goes wrong. Failed transactions, duplicate charges and delayed refunds can damage confidence even when the underlying system is generally convenient. Responsive support and clear communication are therefore important parts of a reliable payments service.
Opportunities for Payment Providers and Merchants
Payment providers can differentiate their services through dependable processing, straightforward integration and tools that help merchants manage transactions. Businesses may value consolidated reporting, simpler reconciliation and payment options that work across in-store and online channels.
Smaller merchants can benefit from payment solutions that are easy to set up and operate without extensive technical resources. Larger businesses may prioritise integration with accounting systems, inventory platforms and customer management tools. Providers that understand these different operational needs can offer more useful services than those focused solely on transaction processing.
According to this industry report, the sector’s projected expansion makes customer experience and operational efficiency important considerations. Providers can build value by combining reliable technology with clear pricing, strong security and practical merchant support.
Business Outlook
Australia’s card payments sector is shaped by changing consumer habits, the adoption of digital wallets and the need for secure, efficient transaction processing. Convenience remains important, but it must be supported by reliable infrastructure, transparent pricing and effective protection against fraud.
For merchants, selecting payment services involves balancing customer preferences, operating costs, security and integration requirements. For payment providers, the opportunity lies in making transactions simpler while maintaining trust across channels. Businesses that address these priorities can support smoother purchasing experiences and stronger customer relationships.