

Every business faces risks that can affect its financial stability, daily operations, employees, and long-term growth. From unexpected fires and equipment breakdowns to employee injuries, transportation losses, cyber threats, and legal liabilities, even a minor incident can create significant financial challenges. While businesses cannot eliminate every risk, they can take preventive measures to minimise its impact through proper risk management and suitable insurance coverage.
However, choosing the right insurance protection requires more than comparing premium amounts. Businesses must understand their risk exposure, evaluate policy conditions, identify coverage gaps, and select insurance solutions that match their operations. This is where Insurance Brokers in India play an important role.
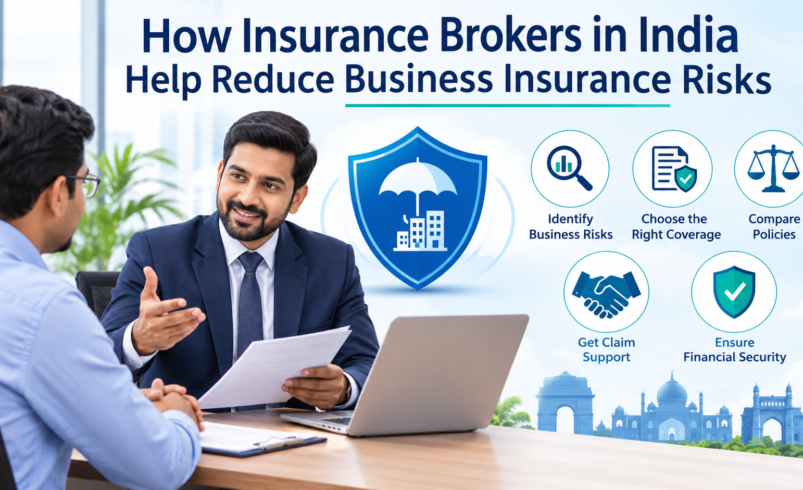
Insurance brokers help businesses assess potential risks, explore suitable insurance products from different insurers, understand policy conditions, and make informed coverage decisions. Their professional guidance can help organisations build a more structured approach to managing financial uncertainties.
Let’s understand how insurance brokers help businesses reduce insurance-related risks and protect their operations.
-
Identifying Potential Business Risks
The first step towards reducing business insurance risks is identifying the situations that could lead to financial losses. Different industries face different challenges, so a standard insurance policy may not provide sufficient protection for every organisation.
For example, a manufacturing unit may face risks involving machinery breakdown, fire, employee injuries, and stock damage. A transportation company may be more exposed to vehicle accidents, cargo damage, and third-party liabilities.
Insurance brokers evaluate business activities and help identify potential risk areas, including:
- Property damage caused by fire, floods, or other insured events.
- Theft of inventory, equipment, or business assets.
- Machinery breakdown and operational interruptions.
- Employee-related accidents and workplace liabilities.
- Goods damaged during transportation.
- Legal liabilities arising from business activities.
- Cyber incidents and data-related financial losses.
This assessment helps businesses understand which risks require insurance protection and where additional coverage may be necessary.
-
Recommending Suitable Business Insurance Policies
Selecting inappropriate insurance coverage can expose a business to unexpected financial losses. An insurance broker helps businesses explore policies based on their industry, operational requirements, asset values, and financial capacity.
Depending on the nature of the business, relevant insurance options may include:
Fire and Property Insurance: Helps protect insured buildings, machinery, furniture, stock, and other business assets against covered fire and specified perils.
Marine Insurance: Provides coverage for eligible goods and cargo during transportation, subject to policy terms and conditions.
Group Health Insurance: Helps employers provide medical insurance benefits to eligible employees.
Workmen Compensation Insurance: Provides protection against specified employer liabilities arising from employee injuries or occupational accidents, as applicable.
Commercial Vehicle Insurance: Helps protect business-owned vehicles against covered risks such as accidents, theft, and third-party liabilities.
Public Liability Insurance: Covers specified legal liabilities arising from third-party injury or property damage associated with business operations.
Engineering Insurance: Helps protect eligible machinery, equipment, and engineering projects against specified risks.
By understanding the available options, businesses can select insurance coverage that addresses their actual operational requirements.
-
Comparing Policies from Multiple Insurance Companies
Different insurance companies may offer different coverage structures, premium amounts, deductibles, exclusions, and additional benefits.
Choosing a policy without comparing these factors can result in inadequate protection or unnecessary expenses.
One of the important functions of insurance brokers is helping businesses compare available insurance options from multiple insurers.
During the comparison process, brokers can help evaluate:
- Premium costs and payment conditions.
- Sum insured and coverage limits.
- Policy exclusions and limitations.
- Deductibles and applicable sub-limits.
- Additional covers and optional benefits.
- Claim procedures and documentation requirements.
This comparison allows businesses to understand the differences between policies rather than making decisions based only on price.
The objective is to identify suitable coverage that balances financial protection and affordability.
-
Helping Businesses Identify Coverage Gaps
Having an insurance policy does not automatically mean that every business risk is covered. Some organisations may have outdated policies, insufficient sum insured, or exclusions that leave important assets and operations exposed.
Insurance brokers can review existing policies and help identify potential coverage gaps.
For example, a business may have property insurance but insufficient coverage for newly purchased machinery. Similarly, a company operating a large vehicle fleet may need to review whether its existing motor insurance arrangements adequately reflect its current operations.
Brokers can help businesses examine:
- Whether the sum insured reflects current asset values.
- Whether newly acquired assets are included.
- Whether business activities have changed.
- Whether important additional covers are required.
- Whether existing policy exclusions create significant exposure.
- Whether coverage limits are appropriate for business operations.
Regular policy reviews can help organisations maintain insurance coverage that reflects their changing requirements.
-
Supporting Business Continuity Planning
Unexpected incidents can interrupt business activities and affect revenue, customer relationships, and supply chains. For some organisations, even a temporary shutdown can create considerable financial pressure.
Insurance brokers can help businesses understand insurance options that support business continuity planning.
For example, business interruption insurance, where available and subject to the applicable policy conditions, can help cover specified financial losses resulting from interruptions caused by insured events.
A broker can help evaluate factors such as:
- Possible causes of business interruption.
- Estimated recovery and restoration periods.
- Fixed operating expenses.
- Dependence on machinery and equipment.
- Supply chain vulnerabilities.
- Appropriate business interruption coverage limits.
Such planning helps businesses prepare financially for unexpected disruptions and understand how insurance can support their recovery.
-
Providing Assistance During the Insurance Claim Process
The real value of insurance becomes evident when a business experiences a loss. However, filing a claim can involve several formalities, including documentation, inspections, notifications, and communication with the insurance company.
Insurance brokers can provide guidance during this process and help businesses understand the necessary procedures.
Their claim-related assistance may include:
- Explaining the claim notification process.
- Helping organise relevant documents.
- Providing guidance on policy conditions.
- Coordinating with the insurance company.
- Following up on claim progress.
- Addressing documentation-related queries.
For instance, if a warehouse experiences fire damage, the business may need to provide policy details, photographs, stock records, invoices, and other supporting documents, depending on the claim requirements.
A broker can help the business understand these requirements and coordinate the process. However, claim approval and settlement remain subject to the insurer’s assessment, policy terms, and applicable regulations.
-
Helping Businesses Manage Insurance Costs
Insurance is an important part of business risk management, but organisations must also maintain control over their operating expenses.
Insurance brokers can help businesses evaluate different coverage options and identify opportunities to manage insurance costs without compromising essential protection.
They may assist businesses by:
- Comparing premiums offered by different insurers.
- Reviewing unnecessary or overlapping coverage.
- Evaluating deductibles and coverage limits.
- Identifying suitable policy combinations.
- Reviewing additional covers based on actual requirements.
- Assessing changes in insurance needs during renewals.
Businesses should remember that selecting the lowest premium is not always the most cost-effective decision. A policy with inadequate coverage may create much higher financial exposure when an unexpected loss occurs.
-
Offering Ongoing Insurance and Renewal Support
Business risks change over time. Expansion, new machinery, additional employees, increased inventory, and new business locations can all affect insurance requirements.
Insurance brokers can support organisations through regular policy reviews and renewal planning.
Ongoing support may include:
- Monitoring upcoming policy renewal dates.
- Reviewing changes in business operations.
- Updating insured asset values.
- Helping arrange policy endorsements.
- Exploring additional coverage requirements.
- Reviewing existing policies for potential gaps.
This ongoing approach helps businesses maintain relevant insurance protection instead of relying on policies that may no longer match their current operations.
Why Should Businesses Work with Professional Insurance Brokers in India?
Working with professional insurance brokers can make business insurance management more organised and convenient. Instead of independently evaluating multiple policy documents, businesses can receive assistance with understanding their insurance requirements and available coverage options.
Some important benefits include:
- Professional guidance: Helps businesses understand different insurance products and policy conditions.
- Multiple insurance options: Provides opportunities to compare available policies from different insurance companies.
- Better risk awareness: Helps identify potential financial exposures and coverage gaps.
- Claim assistance: Offers guidance during claim documentation and coordination.
- Renewal support: Helps businesses review and update their coverage as requirements change.
- Informed decisions: Supports insurance selection based on business needs rather than premium costs alone.
The right broker can become a valuable insurance partner by helping businesses approach risk management more systematically.
Conclusion
Business insurance is not simply about purchasing policies; it is about understanding potential risks and preparing financially for unexpected situations. From identifying operational vulnerabilities and comparing insurance policies to reviewing coverage gaps and providing claim assistance, Insurance Brokers in India can play an important role in helping organisations manage insurance-related risks.
Businesses should evaluate a broker’s IRDAI registration, industry experience, insurer network, policy comparison capabilities, claim support, and customer service before choosing an insurance partner.
Square Insurance Brokers Private Limited, an IRDAI-authorised insurance broker established in April 2017, provides insurance solutions across multiple categories. With access to 53+ insurance company partners and 16+ IRDAI-approved branches across India, Square Insurance helps customers explore insurance options, compare policies, and make informed insurance decisions.
Frequently Asked Question (FAQs)
Q1. How do insurance brokers in India help reduce business risks?
Insurance brokers help businesses identify potential risks, compare suitable insurance policies, understand coverage exclusions, identify protection gaps, and receive assistance during claims and renewals.
Q2. Which insurance policies are important for businesses in India?
Depending on the industry, businesses may require fire insurance, property insurance, marine insurance, group health insurance, workmen compensation insurance, commercial vehicle insurance, liability insurance, and engineering insurance.
Q3. Can insurance brokers help businesses reduce insurance premiums?
Yes. Brokers can compare available policies, review coverage requirements, and help businesses evaluate cost-effective options. However, reducing premiums should not come at the expense of essential coverage.
Q4. Why is risk assessment important before purchasing business insurance?
Risk assessment helps businesses understand potential financial exposures and identify the types of insurance protection required for their operations, assets, employees, and liabilities.
Q5. Can an insurance broker help identify gaps in existing business insurance policies?
Yes. Brokers can review existing policies, examine coverage limits and exclusions, and identify areas where additional or updated protection may be required.